[Note: This article follows the format from a previous article commenting on Daniel Greenstein’s analysis of more than 1,000 private colleges across the U.S., and my thoughts about his analysis, utilizing data from private colleges and universities in Maryland, Virginia, Florida, Pennsylvania, and Iowa. Those articles were written and published in December 2025 and January 2026. I recently updated the data from Maryland and Virginia private colleges and compared the year over year changes. Because North Carolina is a state with more than a few private colleges and universities and was not in my original group of states reviewed, I decided to add it to my analyses to see how different or similar those private institutions are from Maryland and Virginia (and the other states when I update their data).]
Small Private Colleges in North Carolina: the Impact of Scale and Selectivity
In November 2025, Daniel Greenstein (Chancellor Emeritus of PASSHE) published Part 1 of a three-part series about the financial status of public and private institutions. Titled The Fragility of Small Scale, Mr. Greenstein used an “analytical engine” to look at data from 2010 to 2023 to evaluate the financial trajectory of an institution.
A sentence in the introductory paragraph could have been the lead line, stating, “…below about 2,500 students, fragility becomes structural.” Mr. Greenstein wrote that 70-75% of the private colleges whose enrollments are below 2,500 fall into the highest risk category; between 2,500 and 5,000, the risk falls to 60%; at 10,000-20,000, the risk falls to 30%; and above 50,000, it falls to less than 15%.
Greenstein also wrote that small colleges don’t fail because they’re poorly managed. He blamed most failures on “unforgiving economics.” He further wrote that “the fixed costs of accreditation, compliance, technology, student services, and marketing vary only marginally with small size.” The smaller the student enrollment these costs are spread across, the more likely any financial issue is to have catastrophic consequences.
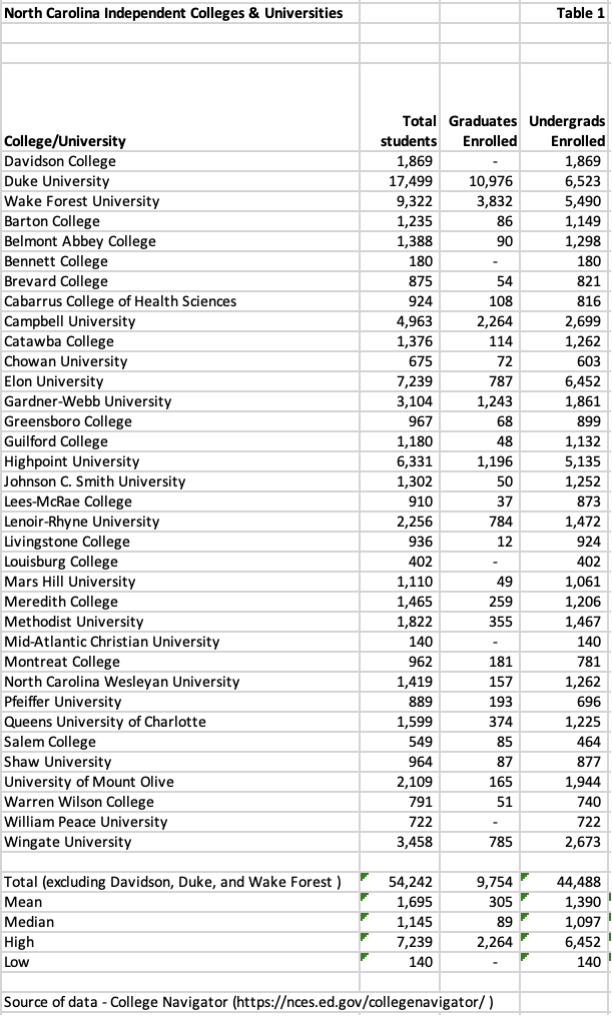
I opted to build a list of North Carolina private colleges and universities using the membership roster of the North Carolina Independent Colleges and Universities (NCICU). I listed the institutions and their total enrollment and undergraduate enrollment in Table 1 below. As you can see, only 7 of North Carolina’s 35 private colleges and universities have enrollments that exceed 2,500. Duke University has the highest total enrollment of 17,499 students, and no other institution exceeds 10,000 students. Wake Forest University is the next largest with 9,322 total students. After Wake Forest, the next-highest enrollment belongs to Elon University with 7,239 students.
Fifteen colleges have total enrollments under 1,000, with the lowest, Mid-Atlantic Christian University, having only 140 undergraduate students. I excluded Davidson College, Duke University, and Wake Forest University from calculations of the mean, median, high, and low for the group for two reasons: their high admissions selectivity and their endowment balances.
Excluding those three institutions, the mean total enrollment for the remaining 32 colleges and universities is 1,695, with a median total enrollment of 1,145. The high is Elon University at 7,239, and the low is Mid-Atlantic Christian University at 140 students.
Liquidity
According to Mr. Greenstein, more than 60% of colleges and universities with fewer than 2,500 students operate with less than a year of unrestricted net assets. This compares to two to three years for mid-sized institutions and five years or more for large research universities.
When a small private institution experiences a poor year of new student admissions, the downturn can trigger a credit downgrade, pressure on debt service, a draw on reserves, further tuition discounting to attract undecided and/or last-minute applicants, and additional downturns.
Tuition Dependence and Price Compression
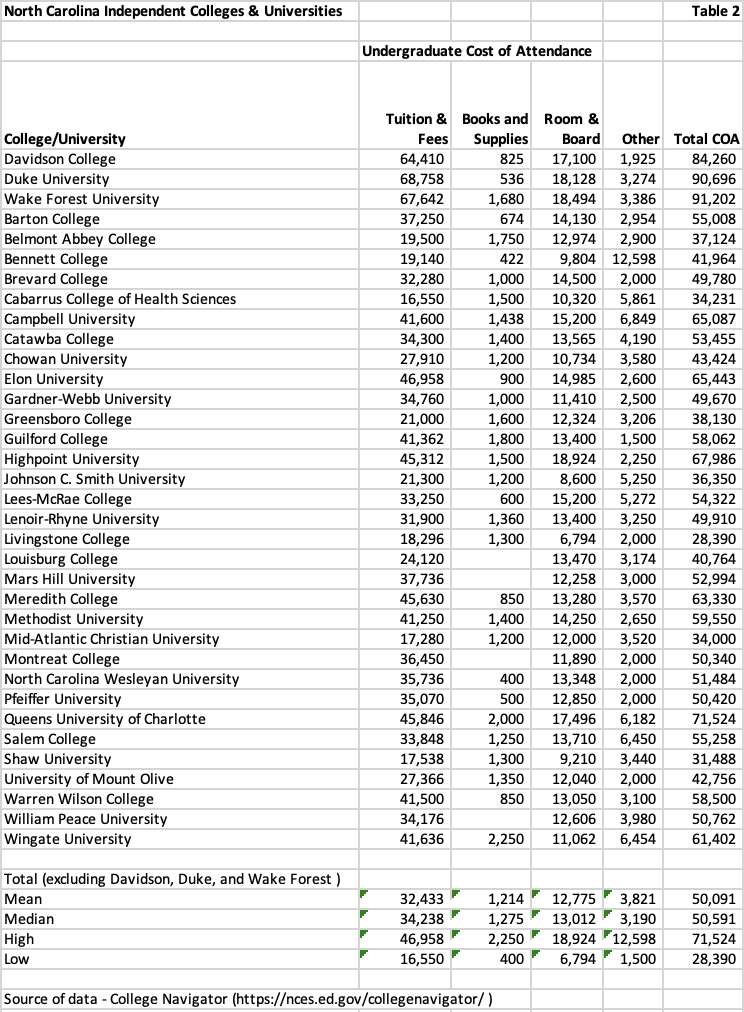
When 85-95 percent of your revenues are driven from tuition and fees, you expose yourself to even greater financial risks in a market with declining enrollments. I created two additional data tables for the 35 NCICU members. Table 2 illustrates the Total Cost of Attendance for each of these institutions, as well as the Mean, Median, High, and Low Values for the 32 institutions other than Davidson, Duke, and Wake Forest. The mean ($32,433) and median ($34,238) tuition rates are similar, although the group of 32 ranges from a low of $16,550 at Cabarrus College of Health Sciences to a high of $46,958 at Elon University. The mean ($50,091) and median ($50,591) Total Cost of Attendance are very close. The low COA ($28,490) is at Livingstone College, and the high is at Queens University of Charlotte ($71,524) (Note: In 2025, Queens University announced that it will merge with Elon University).
There are five “groupings” of Total COA with the following institutions and COA ranges:
Highest: Davidson, Duke, and Wake Forest – $84,000-$92,000
High: Campbell, Elon, High Point, Meredith, Queens, and Wingate – $61,000-$72,000
Middle: Barton, Catawba, Guilford, Lees-McRae, Mars Hill, Methodist, Montreat, NC Wesleyan, Pfeiffer, Salem, Warren Wilson, and William Peace – $50,000-$59,900
Low: Bennett, Brevard, Chowan, Gardner-Webb, Lenoir-Rhyne, Louisburg, and Mount Olive – $40,000 – $49,000
Lowest: Belmont Abbey, Cabarrus, Greensboro, Johnson C. Smith, Livingstone, Mid-Atlantic Christian, and Shaw – $28,400-$39,000
Without a detailed analysis of admissions and marketing materials, as well as a demographic analysis of enrolling students, it is difficult to explain the differences in Total COA below the highly selective group at the top. The most likely explanation for the lower four ranges is “positioning” based on each institution’s targeted demographic group.
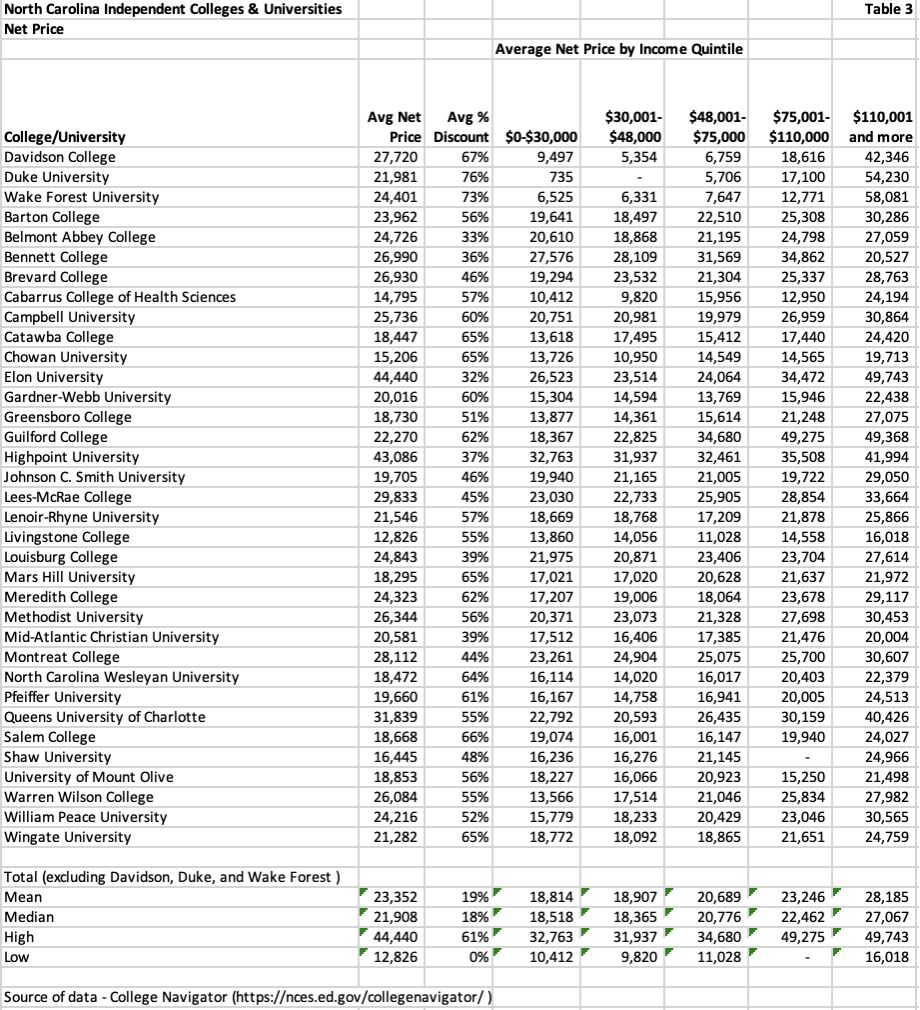
No analysis of the costs of private colleges is complete without looking at net price, which is the Total COA minus all grants. Table 3 below illustrates these numbers for the group. The mean ($23,352) and median ($21,908) average net prices are close (note that these numbers are approximately $3,000 lower than the numbers for Virginia’s private colleges and $6,000 lower than Maryland’s). The institutions, however, range from a low of $12,826 (Livingstone College) to a high of $44,440 (Elon University).
Even though three institutions are excluded from the mean and median analysis, you can see the positive impact of high selectivity and large endowments from the average net price per income quintile, where Duke’s net price of $735 for students whose families’ incomes are in the lowest($0-$30,000) quintile is far less than the mean and median for the other 32 institutions.
When these average net prices are multiplied by the number of undergraduate students enrolled, the product represents 85-95% of total revenues for institutions without significant endowment income or graduate students. Referring to Table 1, there are only five institutions (Davidson, Bennett College, Louisburg College, Mid-Atlantic Christian University, and William Peace University) that do not have any graduate students. Tuition from graduate students makes a difference in survival for some of these institutions. For more discussion about graduate revenues, see Table 5 below.
Enrollment and Market Reach
Small private colleges and universities recruit regionally, not nationally, writes Mr. Greenstein. Proximity matters. The number of high school graduates in the Carolinas is not shrinking as much as in New England, but it’s not growing substantially either. From 2010 to 2023, institutions with fewer than 2,500 students lost an average of 15% of enrollment, whereas the largest institutions grew enrollments. Larger institutions can leverage scale in marketing and recruiting, a benefit that smaller institutions often struggle to achieve.
Program Structure
Small colleges either have too narrow an academic portfolio or too diffuse an academic portfolio, notes Mr. Greenstein. College Navigator, the source of my data for my first article on this subject as well as these tables, has a section for each college/university titled Programs/Majors. Two examples from North Carolina private colleges illustrate his point.
Mid-Atlantic Christian University, the smallest in terms of undergraduate enrollment, had 14 graduates majoring in 7 unique degree programs. With approximately 2,258 bachelor’s degree graduates, Duke University offers 169 different program categories, as listed in the most recent year published by College Navigator. A narrow focus can restrict the number of students interested in your college. A too diffuse portfolio may generate instructional cost inefficiencies. In Duke’s case, its endowment balance and graduate tuition revenues are subsidizing some of its very low-enrollment programs.
What Scale Buys
When enrollments reach or exceed 10,000 students, a shift occurs, according to Mr. Greenstein’s analysis. Operating margins are positive. Tuition dependency is less than 60%. Endowment balances per FTE (full-time equivalent) student increase, and external funding increases.
The efficiencies from scale allow institutions to buy the following:
- Revenue diversification among graduate programs, auxiliaries, philanthropy, and research.
- Fixed cost overhead is spread across more students.
- Market elasticity – national reach offsets regional/local decline
- Brand leverage – selectivity sustains price integrity
The Leadership Paradox
According to Mr. Greenstein, there are a few small enrollment institutions that are not at risk. These are wealthy liberal arts colleges with large endowments and loyal alums. In North Carolina, Davidson College falls into this not-at-risk category.
Most presidents of small private colleges face the following challenges:
- Raise price and risk yield
- Cut price and erode margin
- Diversify and dilute mission
- Consolidate and lose identity
The math doesn’t work well without scale. Collaborations offer some relief, but most colleges lack the flexibility to initiate such partnerships within a reasonable timeframe. Waiting deepens the financial decline, and few partnership opportunities are available to financially distressed institutions.
The Price of Admission
Daniel Greenfield followed up his research piece on scale with an article on admissions selectivity in private colleges and universities. He opened by saying, “Across nearly 1,000 private institutions, we see a simple, if sobering, pattern: As acceptance rates rise, financial resilience collapses.” He further writes that the relationship is not linear but is exponential. “Beyond 50% acceptance, the decline becomes a free fall. By the time acceptance exceeds 75%, nearly 9 out of 10 institutions are considered high risk.
I added to the tables of data for NCICU institutions that I created for his earlier paper. In Table 4 below, I have included College Navigator statistics for the number of applications, the percentage accepted, and the percentage that enroll for each of the institutions. Again, I did not include Davidson, Duke, and Wake Forest in the group’s mean and median statistics.
Based on Greenfield’s research on admissions selectivity, many of North Carolina’s private colleges and universities could be considered high risk. Excluding the three previously mentioned institutions, the lowest acceptance rate is 23% at Cabarrus College of Health Sciences. Four institutions (Barton College, Pfeiffer University, William Peace University, and Wingate University) are essentially open-enrollment, with acceptance rates exceeding 90% for applicants. The mean admit rate for the group of 32 is 71%, and the median is 75%.
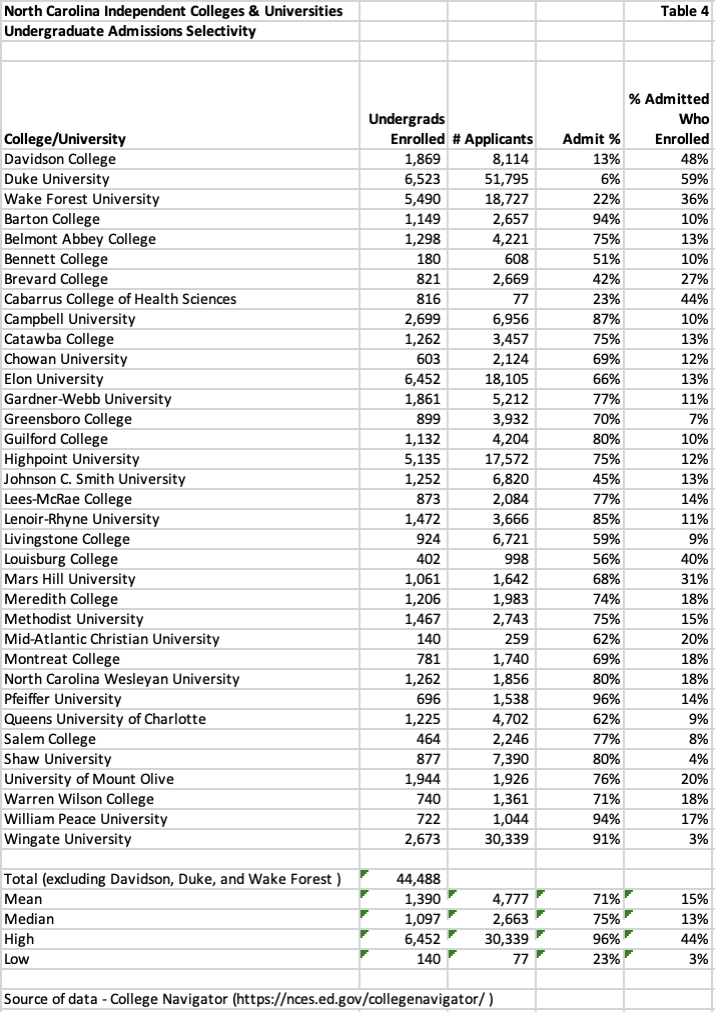
Greenstein’s paper discusses differences in financial risk across institutions with acceptance rates below 10%, between 10% and 25%, between 25% and 50%, above 50%, and above 75%. Note that only one private institution in North Carolina has a single-digit acceptance rate (Duke), and Davidson (13%) and Wake Forest University (22%) are the next-lowest institutions.
When the acceptance rate exceeds 50%, Greenstein notes that liquidity falls below 75% and tuition dependency surpasses 80%. Institutions are trapped in a spiral of shrinking enrollment, rising discounts, eroding net tuition, and collapsing unrestricted assets. By reaching a 75-85% acceptance rate, most institutions exhibit 3-5 signs of financial decline. At 85-100% acceptance, tuition accounts for 90% of revenue, reserves are almost nonexistent, and financial distress is structural, not cyclical.
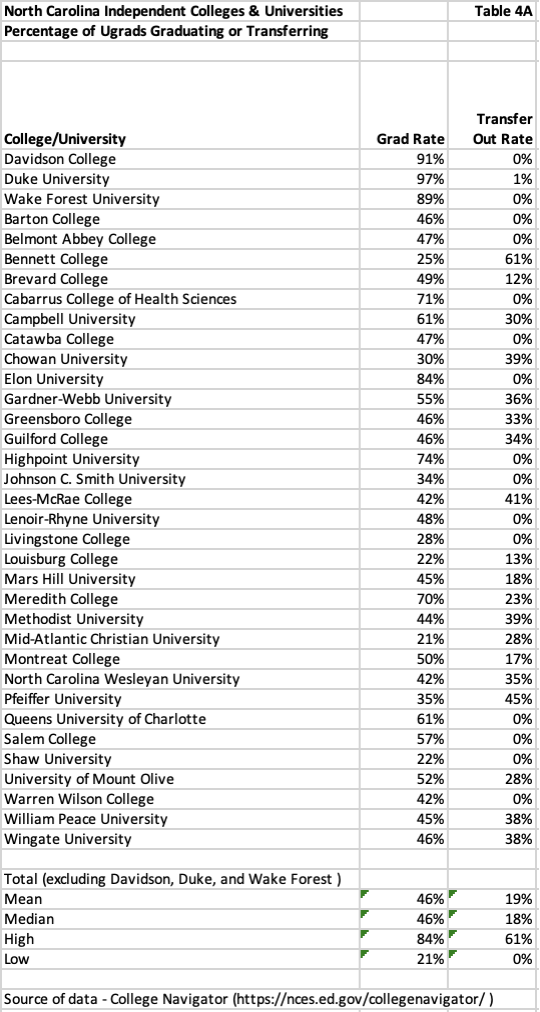
With low selectivity, the first thing that comes to mind is the percentage of enrolled students who graduate. Table 4A below illustrates the percentage of undergraduates who graduate in six years, as well as the percentage of first-year students from that starting cohort who transfer out. The group of 32 varies significantly. The mean and median for the group of 32 is 46%.
Four colleges have graduation rates of 25% or lower. The mean and the median transfer-out rates are high compared to Davidson (0%), Duke (1%), and Wake Forest (0%). The high transfer-out rate is Bennett College at 61%. Pfeiffer University has a 45% transfer-out rate, and Lees-McRae has a 41% transfer-out rate. Obviously, the larger the transfer-out rate, the lower the overall undergraduate tuition revenues for the institution.
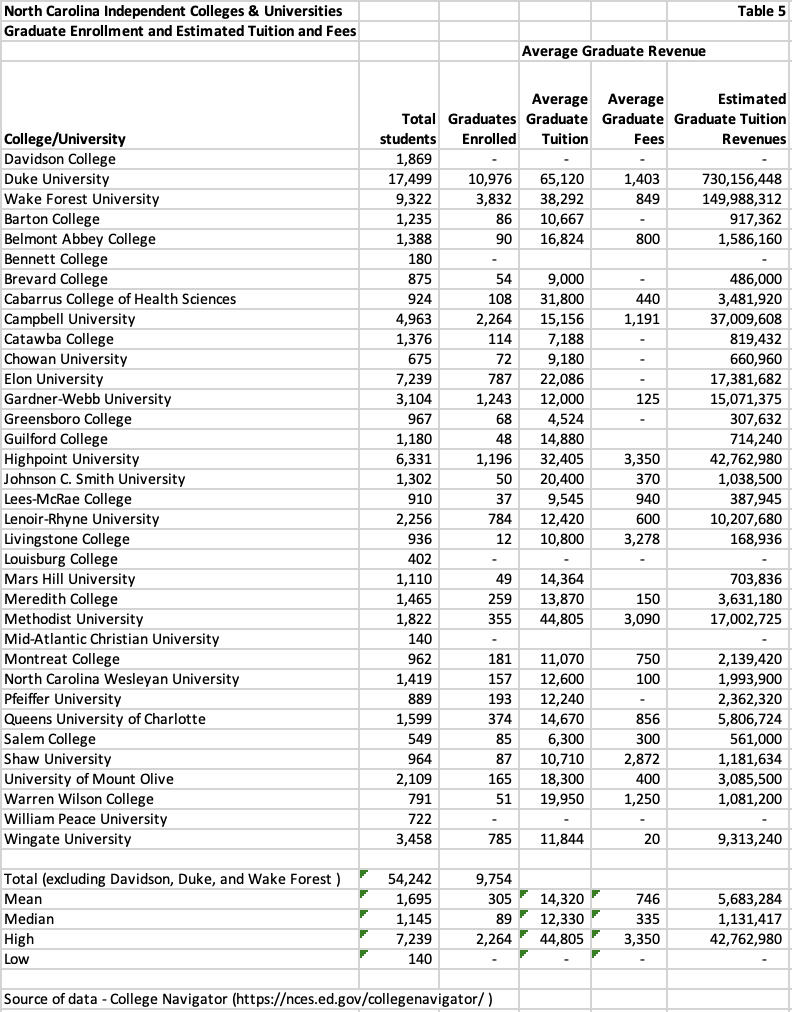
Naturally, there are always exceptions, and it appears that some NCICU institutions are offsetting non-selective undergraduate enrollments with graduate enrollments. In Table 5 below, I used the average graduate tuition and fees for each institution and multiplied them by the number of graduate students to derive an estimated graduate tuition revenue. While this may not account for financial aid or discounts, it’s a relatively useful tool for gauging how much revenue each institution generates from its graduate programs.
With 10,976 graduate students at an average tuition rate of $65,120, Duke University is off the charts with an estimated $730 million in graduate revenues. The mean ($5,683,284) and median ($1,131,417) estimated graduate tuition revenues for the other 32 colleges and universities are quite different but indicate how graduate tuition revenues can enhance the colleges’ financial situation.
The range of estimated graduate tuition revenues for the other 32 institutions goes from a high of $42,762,980 at High Point University to a low of $0 at five colleges with no graduate students.
Selectivity matters because “it is a proxy for pricing power and brand elasticity.” Institutions have the power to control pricing without offsetting demand. Beyond 50% acceptance, the market sets the tuition price, and institutions’ margins decline as the net price decreases. Institutions with acceptance rates of more than 50% are part of the overcrowded, price-sensitive higher education market.
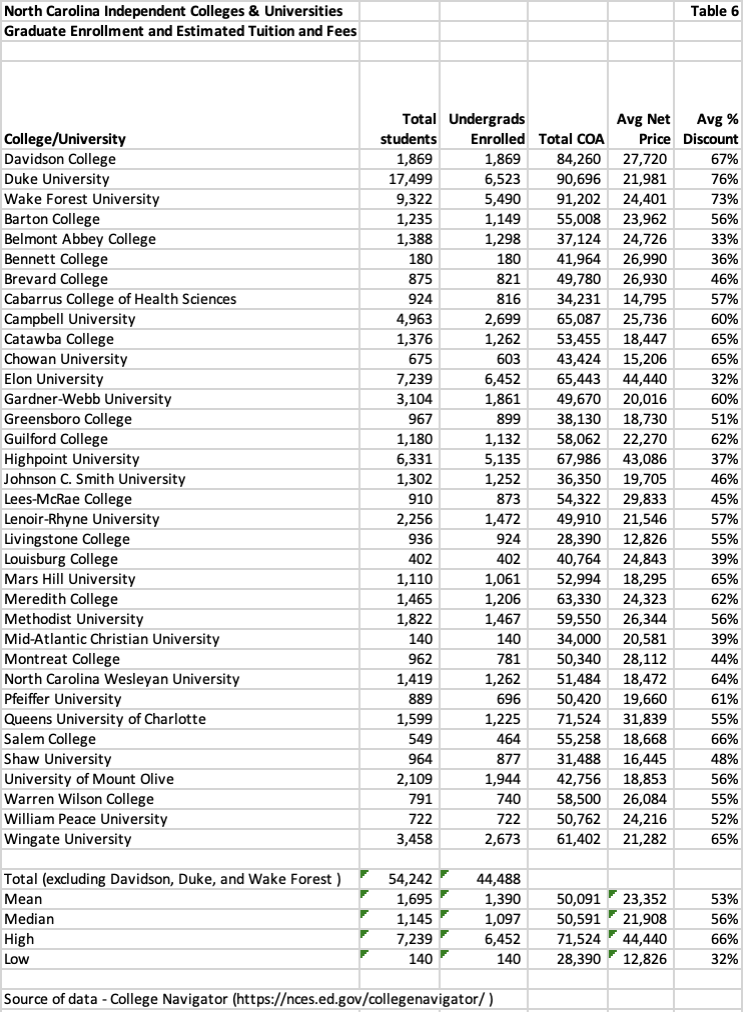
Although Mr. Greenstein emphasized the net price as the primary source of cash for institutions without large endowments, it’s also important to consider the discount percentage (1 minus the average net price divided by the total cost of attendance) to assess the market’s impact on pricing. In Table 6 below, the net discount percentage is calculated for each of North Carolina’s private colleges.
Davidson, Duke, and Wake Forest offer grants averaging around 75%, but the funds drawn from their endowments likely cover a high percentage of that discount. The remaining 32 colleges have a mean average tuition discount percentage of 53% and a median average tuition discount percentage of 56%.
The highest (or steepest) average tuition discount percentage for the group of 32 is at Salem College, with a rate of 66%. The lowest average tuition discount percentage is at Elon University, with a rate of 32%.
The low selectivity across almost all these institutions, combined with the high average discount rate, illustrates the market-dependency issue emphasized by Mr. Greenstein. Salem College has the highest average discount rate (66%) and a higher-than-the-mean and median admission rate of 77%.
Mr. Greenstein notes that each of the 1,000+ institutions in his dataset was scored on approximately 36 financial and operational metrics. Among these were liquidity, margin, tuition dependency, enrollment trends, and cost structure.
Risk archetypes appear in layers when institutions have low selectivity, writes Greenstein. Enrollment fragility and tuition dependency appear in nearly every institution. Academic program sprawl and financial distress appear as liquidity erodes.
Greenstein writes that the conclusion from this data analysis should not be that colleges need to increase their selectivity. Selectivity defines the institution’s structural position, as well as the pricing power and market elasticity it commands. Strategy should be guided by an understanding of the position, not by trying to increase selectivity.
Greenstein recommends that institutions with an acceptance rate of more than 70% should consider scale initiatives such as:
- Collaborating with other institutions to share administrative and technology costs
- Specializing in mission or program areas where competition is low
- Diversifying through adult, online, or workforce-aligned programming
- Partnering with states or systems to simulate the economies of scale that you lack
He also recommends considering financial restructuring or mergers before financial reserves are depleted. Greenstein did not recommend adding graduate programs, but the third bullet could theoretically include graduate programs (in my opinion).
Where an institution is on the selectivity curve matters, writes Greenstein. Elite colleges have room to adjust their operating models without compromising their stability. Open enrollment institutions (with 100% acceptance rates) do not. Institutions in the middle have too much cost to shrink and too little market to grow. Once the market takes over, the odds of recovery diminish rapidly.
A Few More Thoughts
I found both of Mr. Greenstein’s studies to be informative. While some of the findings are intuitive (increased tuition discounting leads to decreased operating margins, for example), having a dataset of over 1,000 institutions to use for analysis is impressive. Building my own small dataset utilizing enrollment, tuition, net price, and admissions selectivity for 35 private institutions in North Carolina (plus the private institutions in Virginia, Maryland, Florida, Pennsylvania, and Iowa) allowed me to grasp the significance of Greenstein’s findings as well as the market situation impacting many of our private institutions.
North Carolina’s private colleges and universities have a lower total cost of attendance than those in Maryland and Virginia. I believe that’s more aligned with the higher percentage of North Carolina’s private colleges located in rural areas, compared with Maryland’s urban and higher-cost-of-living areas. I’m not sure about the reason for the difference between North Carolina and Virginia since both states appear to have more than a few rural colleges. It appears that increasing enrollment will be challenging for many of these institutions, particularly those with the highest admit rates and the lowest enrollments. The demographic cliff is here, and that won’t make it easier to recruit new students.
Most senior administrators working for at-risk private institutions are aware of many of these challenges. The findings of Greenstein’s research may be more relevant for their board members as they consider strategies for success or survival.